

Family offices tend to approach AI with three hats on. The three areas do often overlap, but each one brings a different focus.
The first is the running of the office itself: day-to-day operations like other small businesses, how it works, and what it costs to operate. The second is the business or businesses the family owns or controls, where AI shifts the cost structure, the headcount and the competitive position, and where the consequences land directly on the family. The third is the investment portfolio.
Each of these needs a distinct approach. The third is the one to look at today, because over the last few weeks that hat has been busy.
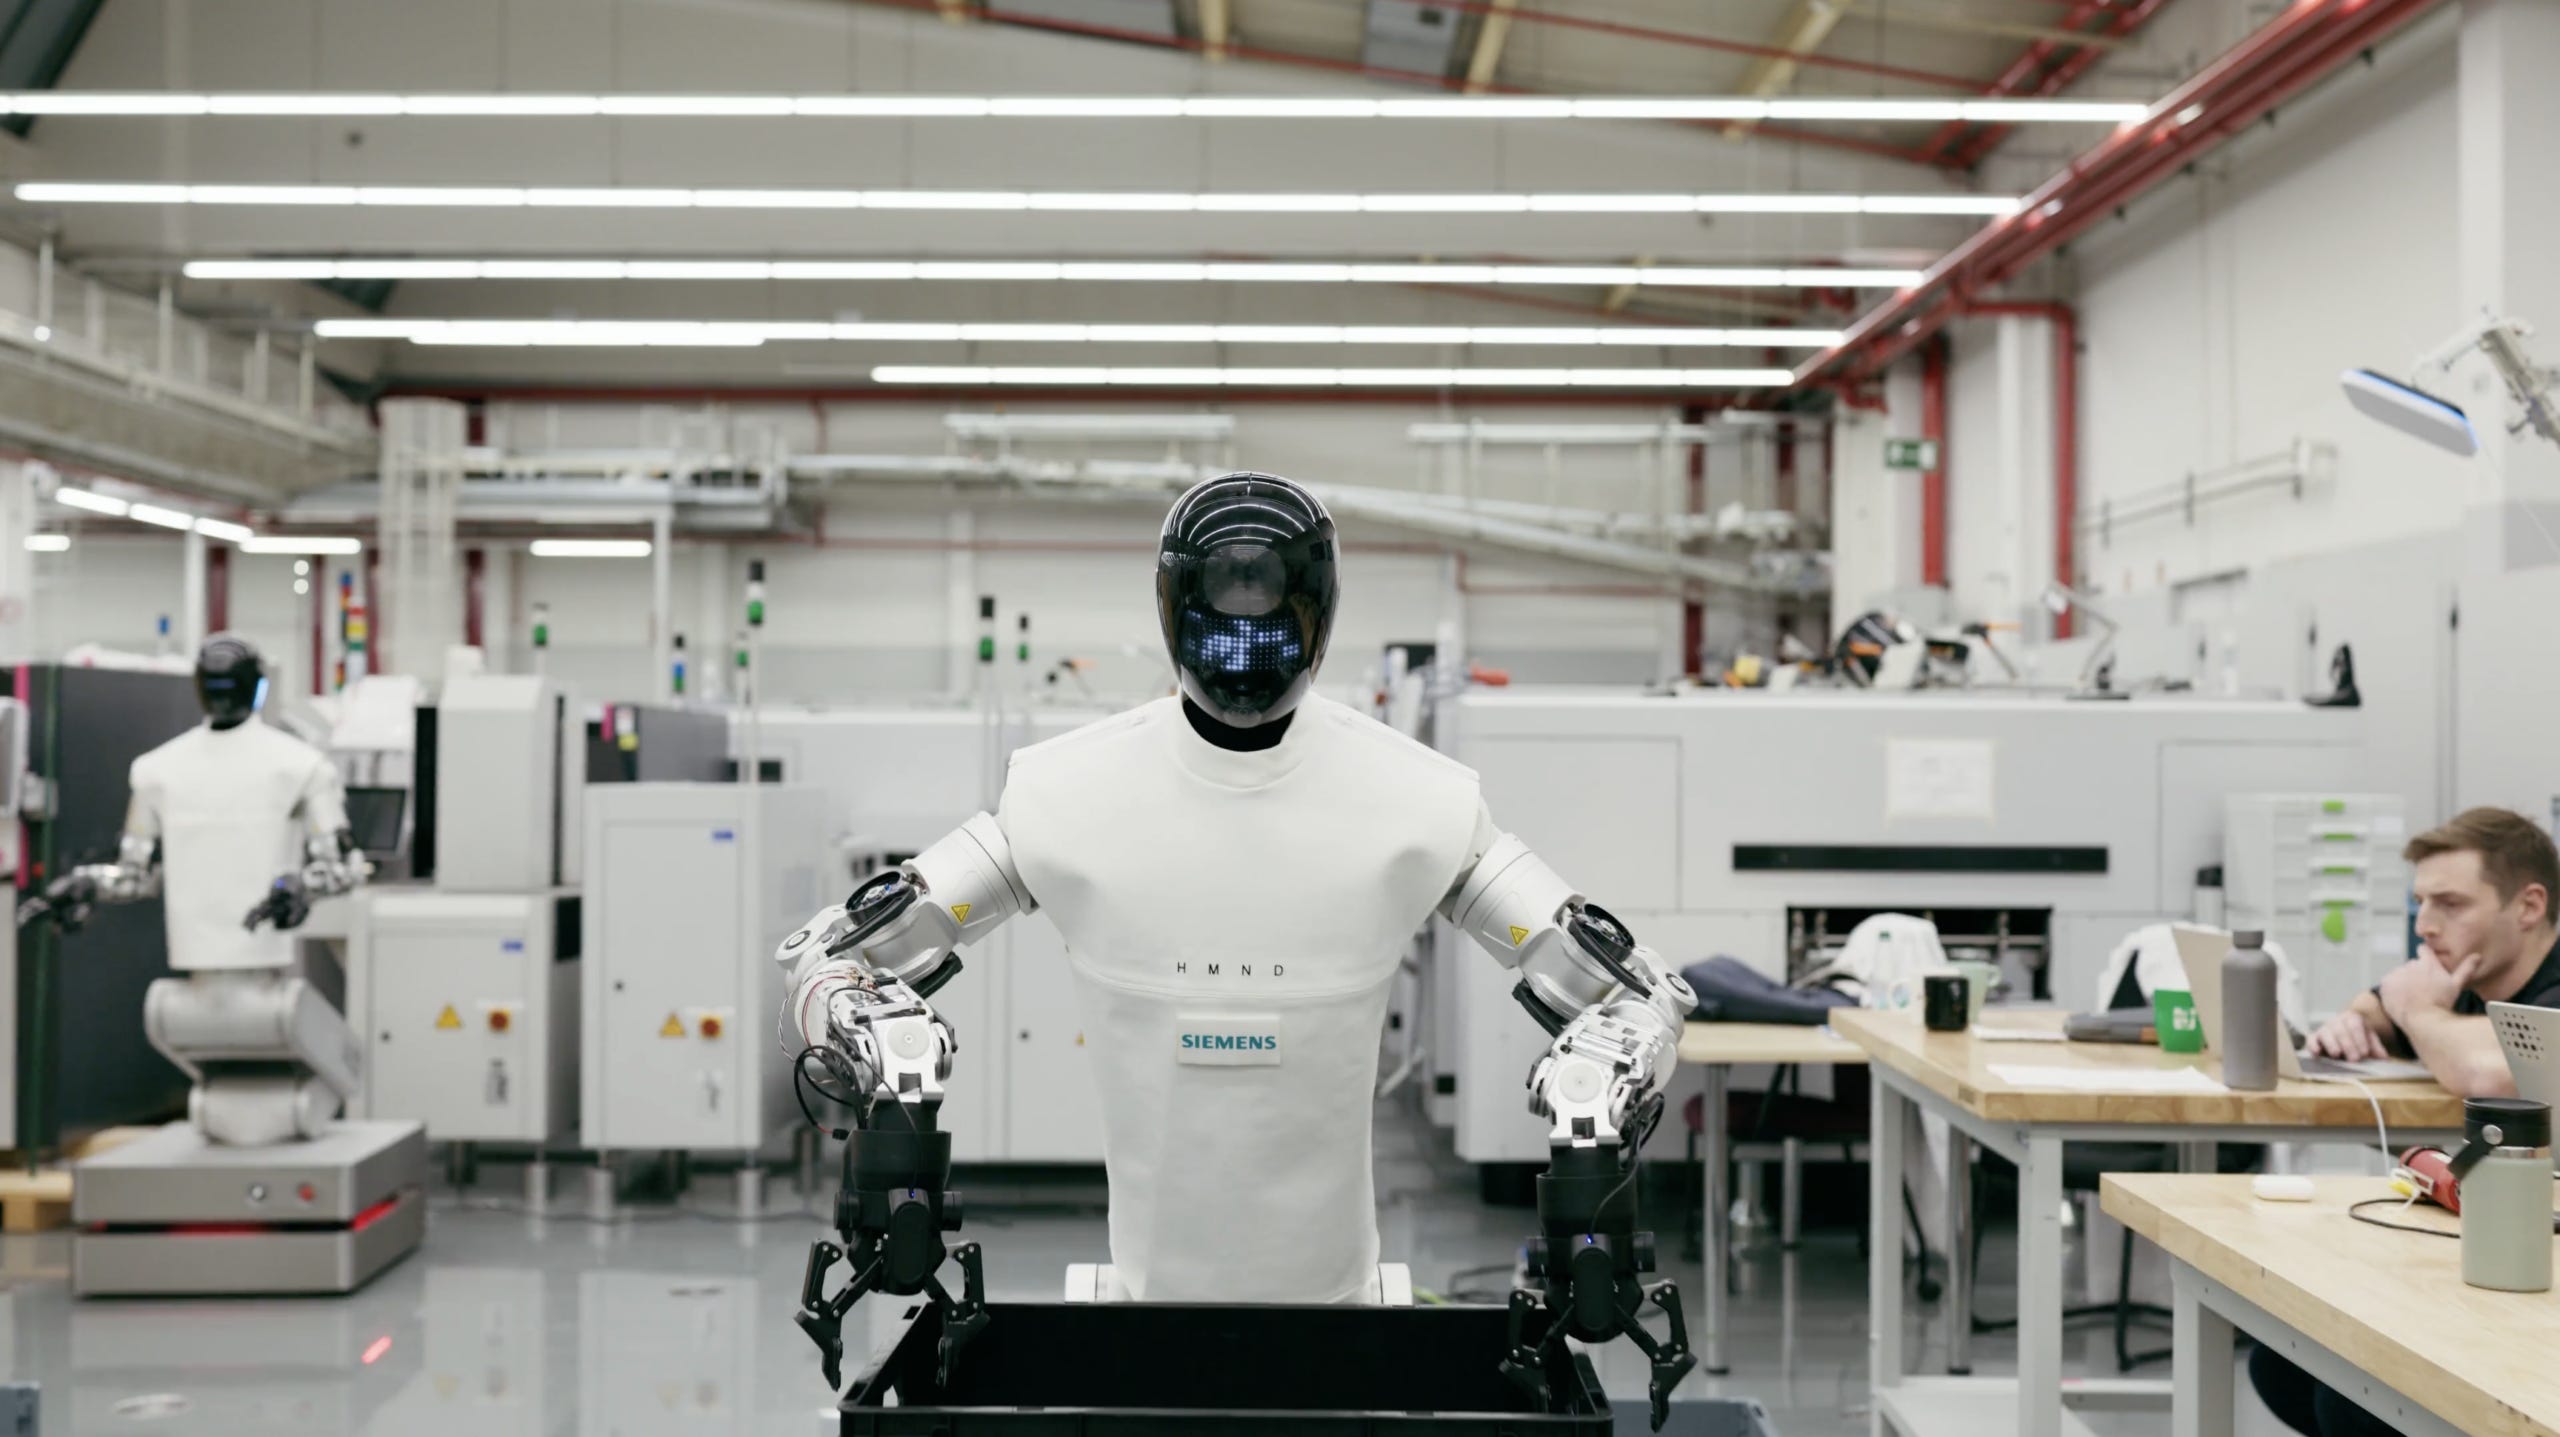
The venture unit of Bernard Arnault’s family office took part in a Series A round for Humanoid, a London-based developer of industrial robots. Bezos’ family office increased its investment in Generalist AI, a software company focused on robotics. And Azim Premji’s family office is reported to be negotiating the lead position in a new funding round for a developer of general-purpose robots with offices in Paris and Silicon Valley. The combined net worth of those three people is about $628.5 billion, and none of those fortunes was made with AI.
It’s showing up everywhere. Luxury goods, retail logistics and Indian software services are buying robots, even though they made their money somewhere completely different.
AI For Family Offices
Interested in learning more about AI transformation for family offices?
We have a framework and work with different stages and journeysl
Bodies, brains and blood draws
The coverage has treated this as a single trade. It is however at least three very different types of investments, and each carries a different risk profile.
The first level is the humanoid, or the general-purpose platform. Humanoid in London belongs here, as does the company Premji’s office is circling. These are bets on a body that can do anything, which is a massive prize to win and a very long way from generating revenue. Barclays puts the humanoid market at $2 to $3 billion today, reaching $200 billion by 2035, a figure that illustrates the enthusiasm around this trend and says very little about the cash flow.
The second level is the software that powers the machines. The Bezos investment in Generalist AI fits here. It is the more tenable position, because a software layer can charge a royalty regardless of whose body ends up winning.
It is the picks-and-shovels model, except the shovels write policies and the picks run training loops.
The third level is vertical automation with a customer already in place. Dan Friedkin’s family office went into RobCo’s Series C alongside a money manager for Italy’s Agnelli family. Alpha Square Group invested last month in Atoms, the industrial robotics company founded by Travis Kalanick. And Harald McPike’s family office backed the Series B for Vitestro, a Dutch company building autonomous blood-drawing systems.
Blood draws are a task. A hospital performs thousands of them a day, using staff it struggles to recruit, at a cost per draw it already knows to the penny. You can build a model around that. You can estimate the hours of labour saved and the throughput gained, and within eighteen months you will know whether you were right.
You only get that at the third level. Worth being sure which level you are actually at, rather than assuming you have diversified your physical AI exposure.
Shopping on sale
Those cheques went out at an interesting time, while the share prices of companies along the AI supply chain were being marked down over concerns about spending. Investors more patient than the rest of the market bought into positions others were leaving, which is the family office structural advantage working in practice.
The demand is widespread. UBS surveyed 307 family offices across more than 30 markets, overseeing $1.3 billion on average for families worth $2.7 billion, and found AI to be the leading investment theme. Some 65% have invested somewhere across the AI value chain, and offices in the US, Asia and Latin America say they intend to allocate more over the coming year. James Whittaker of Deutsche Bank, who runs wealth management for the UK and Nordics, says robotics is coming up frequently in client conversations.
Few investors can hold a position through a decade of execution risk, and family offices are among them. That is only an advantage, though, if you can afford to be wrong for five years and hold anyway, which is a different question from how much you can afford to put in.
Talk to the operator, not the founder
Family offices can do something funds cannot, and it has almost nothing to do with fees.
In that same UBS survey, over three-quarters of owners were still active in their own businesses, mostly in real estate, consumer goods and financial services. Which means warehouses, production lines, a hotel floor, a clinic, a delivery fleet, somewhere a machine either survives reality or does not.
Most people investing in this area are reading somebody else’s pilot study. You can run your own. Put the robot in your own building, on the night shift, working alongside your own staff, and you will learn more in a quarter than a room full of data will tell you in a year.
Access to deployment is due diligence, and almost nobody uses it that way.
So, three things to do with the next one. Get the name of a live deployment, and speak to the operator rather than the founder. Ask what broke at the third site, because the first site always works. And favour the ventures where somebody is already paying for the labour in question.
One more point, which takes us back to the first hat. Being able to deploy this technology across the group’s operations is a claim about competence at home. If your own office cannot say which model performs which task, or what the reporting pipeline costs to run each month, then the deployment advantage is a hypothesis rather than an edge.
Jensen Huang, promoting Nvidia’s own robotics work, put it about as plainly as it can be put: physical AI is here.
About the author
Francois Botha helps design and incubate the family offices of the future through Simple, which pairs high-touch advisory with technology-led solutions to help private wealth owners build offices that last. From formation and strategy through to AI-powered operations, Simple’s team and network of independent advisors provide the knowledge, agentic tools, and governance to move forward with confidence, while keeping the human judgment that matters most at the centre.
He wrote a weekly column on family office strategy for Forbes and speaks regularly at private wealth, family office and technology events.