


Last week, Anthropic told its subscribers that their $200-per-month Claude Max subscription would no longer cover third-party AI tools.
In other words, Anthropic has ended access for Claude in third-party tools.
AI has practically felt free for the past two years. Subscriptions were subsidised, usage was unmetered, and the whole thing cost less than a team lunch.
Now, want to run agents outside Anthropic’s own products? Then it’s pay-as-you-go.
Under pay-as-you-go extra usage, per-interaction costs are estimated at $0.50 to $2.00 per task, which makes heavy agentic use expensive in ways that a fixed monthly plan obscured.
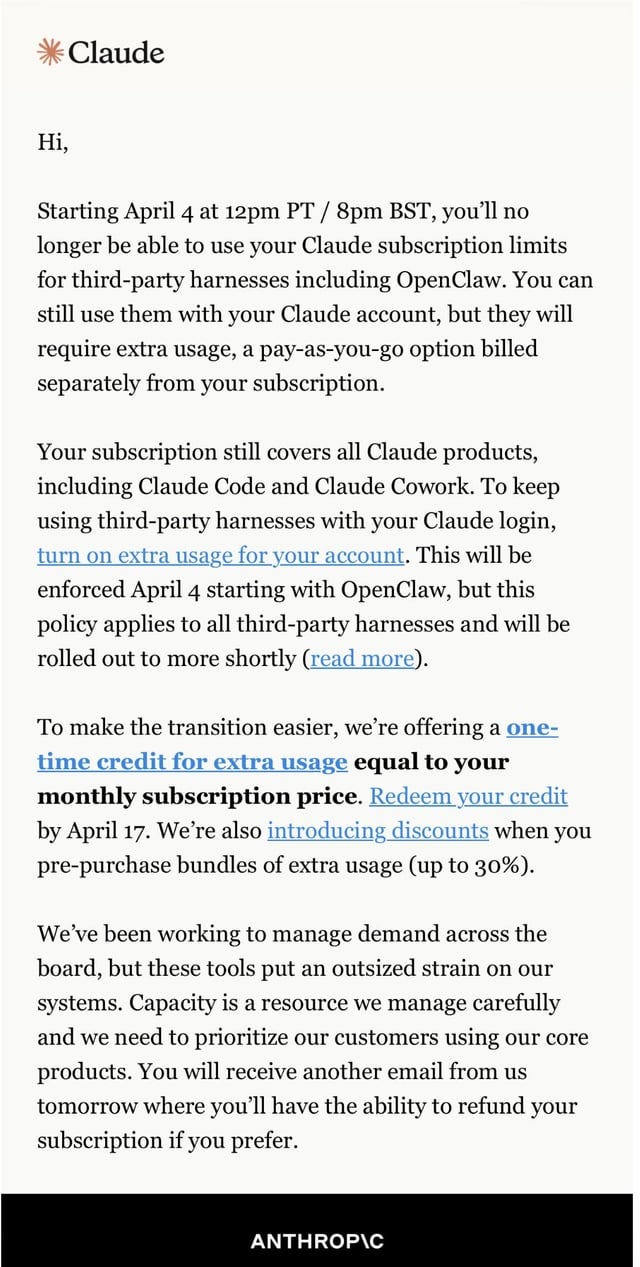
(Screenshot: Email from Anthropic to Claude subscribers, April 3, 2026. Announcing that subscription limits will no longer cover third-party tools, including OpenClaw, effective April 4.)
The same week, a startup called Kuse AI launched Junior, an AI “employee” built on one of those now-cut-off tools.
It updates your CRM, drafts campaigns, and generates reports. The price: $2,000 a month. Over 2,000 companies joined the waitlist before it even launched.
Two-hundred dollars for the AI model and two thousand for someone to make it do something useful.
This is the new economics of AI and if you’re running a family office, it’s worth understanding before it shows up on your P&L.
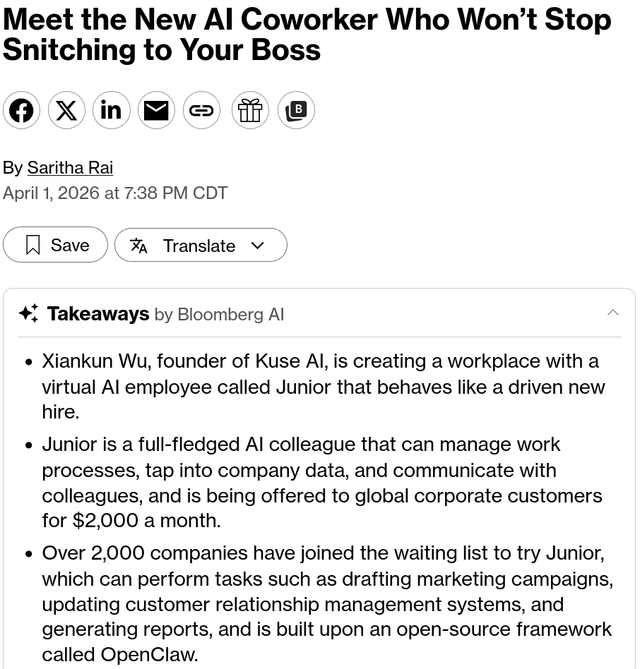
(Source: Bloomberg, “Meet the New AI Coworker Who Won’t Stop Snitching to Your Boss,” Saritha Rai, April 2, 2026. Kuse AI’s Junior is a $2,000/month AI employee built on OpenClaw, with over 2,000 companies on the waitlist.)
The Flat-Rate Era Is Over
Now that AI has been embedded in day-to-day workflows for the past few years, the correction of pricing to usage is underway. Anthropic is the latest, but the pattern is industry-wide.
Ramp data shows that businesses’ monthly AI spend grew 4x between February 2025 and February 2026. Gartner projects global spend on AI services and software will hit roughly $1 trillion this year.
And most of that spend is unmanaged. 80% of companies miss their AI spend forecasts by 25% or more. 78% of IT leaders report being hit by unexpected AI-related charges. The adoption curve is outpacing every previous technology and the financial controls haven’t caught up.
This sounds like an enterprise cost management problem. But family offices, with lean teams and no dedicated IT function, are more exposed than most.
The hardware story is flipping
The pricing shift isn’t only going one way. RAM prices, which had been climbing for months as AI data centres competed for global supply, started falling in late March. DDR5 prices dropped more than 20% in a single month.
Two things caused it. OpenAI quietly walked back some of its hardware commitments. And Google released TurboQuant, a new compression technology that shrinks AI’s working memory by 6x and runs 8x faster. If the models need less hardware to do the same work, the forecasts that pushed prices up look overstated.
The point isn’t that AI is getting cheaper or more expensive. It’s that the numbers are moving in both directions at once, and fast. A cost line that looked fixed three months ago may be half that today, or double.
For any family office trying to plan AI spend, the only useful position is knowing what you’re using and why, because the market around you won’t hold still.
The real cost of making AI work
For every dollar spent on an AI model, businesses are spending $5 to $10 making that model production-ready, which includes integration, compliance, monitoring, and ongoing governance.
The model itself is the smallest line on the invoice. The expensive part is everything around it.
Anyone running a family office recognises this pattern. You don’t just buy a fund platform; you pay for configuration, data migration, reconciliation, and reporting.
The tool is the entry ticket, but the value and the cost are in making it work for your specific context.
The question was never “how much does the tool cost?” It was always “how much does it cost to make it work for us?”
AI is no different, as the model is the commodity. The implementation is the investment. And like any serious investment, the returns should justify the spend.
The family offices getting this right aren’t the ones spending the least on AI. They’re the ones who know exactly what they’re spending, why, and what they’re getting back.
What to do this quarter:
Audit what your team is already using: A lot of family offices have team members running AI tools on personal subscriptions or expensing them without oversight (AI shadowing). With AI spend growing 4x year-on-year across businesses, even modest adoption adds up fast. You can’t manage what you can’t see.
Separate the model cost from the implementation cost: When evaluating any AI tool or vendor, ask what you’re really paying for. If the value sits in the wrapper, the workflow, the integration, or the governance layer, price it accordingly. The $5-to-$10 ratio is a useful benchmark, not a red flag. It’s what serious deployment looks like.
Budget for AI like you budget for advisory: AI is moving from a rounding error to a real line item. Finance leaders across industries are already demanding that AI deployments justify their spend. Family offices should hold the same standard, not to slow adoption down, but to make sure every dollar is working.
The AI engine has never been cheaper, but the mechanic has never been more expensive. The family offices that understand the difference and plan for it won’t just adopt AI to improve efficiency; they’ll get real returns from it.
This edition of Field Notes was written by Oliver Yorke, Head of Community & Growth.
If your family office is thinking about where AI fits into your system, we’d love to hear what questions you’re working through - drop us a note at hi@andsimple.co.
And what caught our attention this week:
A few things the Simple team has been reading, testing, or talking about.
Tools we tried:
Simple Accounting Tool (led by Philip): We at Simple are using our accounting team’s chatbot that is integrated with our accounting system. More to share next week.
Atlassian Remix (open beta): Turns data and information stored in Confluence into charts and graphics without requiring separate applications, with three new third-party agents via MCP integrations with Lovable, Replit, and Gamma.
Worth reading:
Raffy Marty’s AI Is Becoming a Company Operating System Layer captures the shift happening in PE/VC diligence: the question is no longer “what’s your AI strategy?” but “how far along are you in rebuilding around AI?” Companies bolting AI onto old operating models will lose to those rebuilding from the foundation up on speed, learning rate, and unit economics.
Google’s Jules V2 (Jitro) shifts AI coding agents from task-execution to goal-setting. The agent autonomously identifies what needs to change in a codebase to hit a metric, rather than waiting to be prompted. Expected ahead of Google I/O (May 19). The trust barrier, not the capability barrier, will determine adoption speed.
LessWrong with We’re Running Out of Benchmarks makes the case that our ability to upper-bound AI capabilities is quietly collapsing. Claude Opus 4.6 now passes 80%+ of METR’s long-horizon task suite, making capability ceilings effectively unmeasurable. By mid-2027, no 2026-era benchmark may be able to rule out dangerous capabilities. The governance infrastructure problem is arriving faster than most realise.
Capital signals:
NeuBird AI, a San Francisco, CA–based agentic AI company for enterprise production operations, has raised $19.3 million in a funding round.
Insight Health has raised a Series A $11 million round. Standard Capital led the round with participation from Pear VC, Kindred Ventures, Eudemian, ElevenLabs and 43, Voice and chat AI agents to handle routine clinical admin work.
Rhoda AI exits Stealth after 18 months with $450 million in Series A funding, unveiling a robotic intelligence platform. Backers include Temasek, Khosla Ventures, Capricorn, and John Doerr.
Steno, an AI-native legal services company combining court reporting with generative AI, raised a $49M Series C, backed by Insight Partners and Index Ventures.
The $5-10 implementation cost for every $1 of model cost is the number that keeps getting ignored in the pricing conversation. Everyone is tracking token prices, which are falling. Almost nobody is tracking the surrounding cost stack, which isn't. Pulling subscription coverage for third-party tools is significant because it forces that real cost to surface. A lot of teams were treating AI as cheap because the headline number was cheap. The actual bill is integration, monitoring, prompt maintenance, and handling the failures that happen at production volume.